Source: reinsurancene.ws
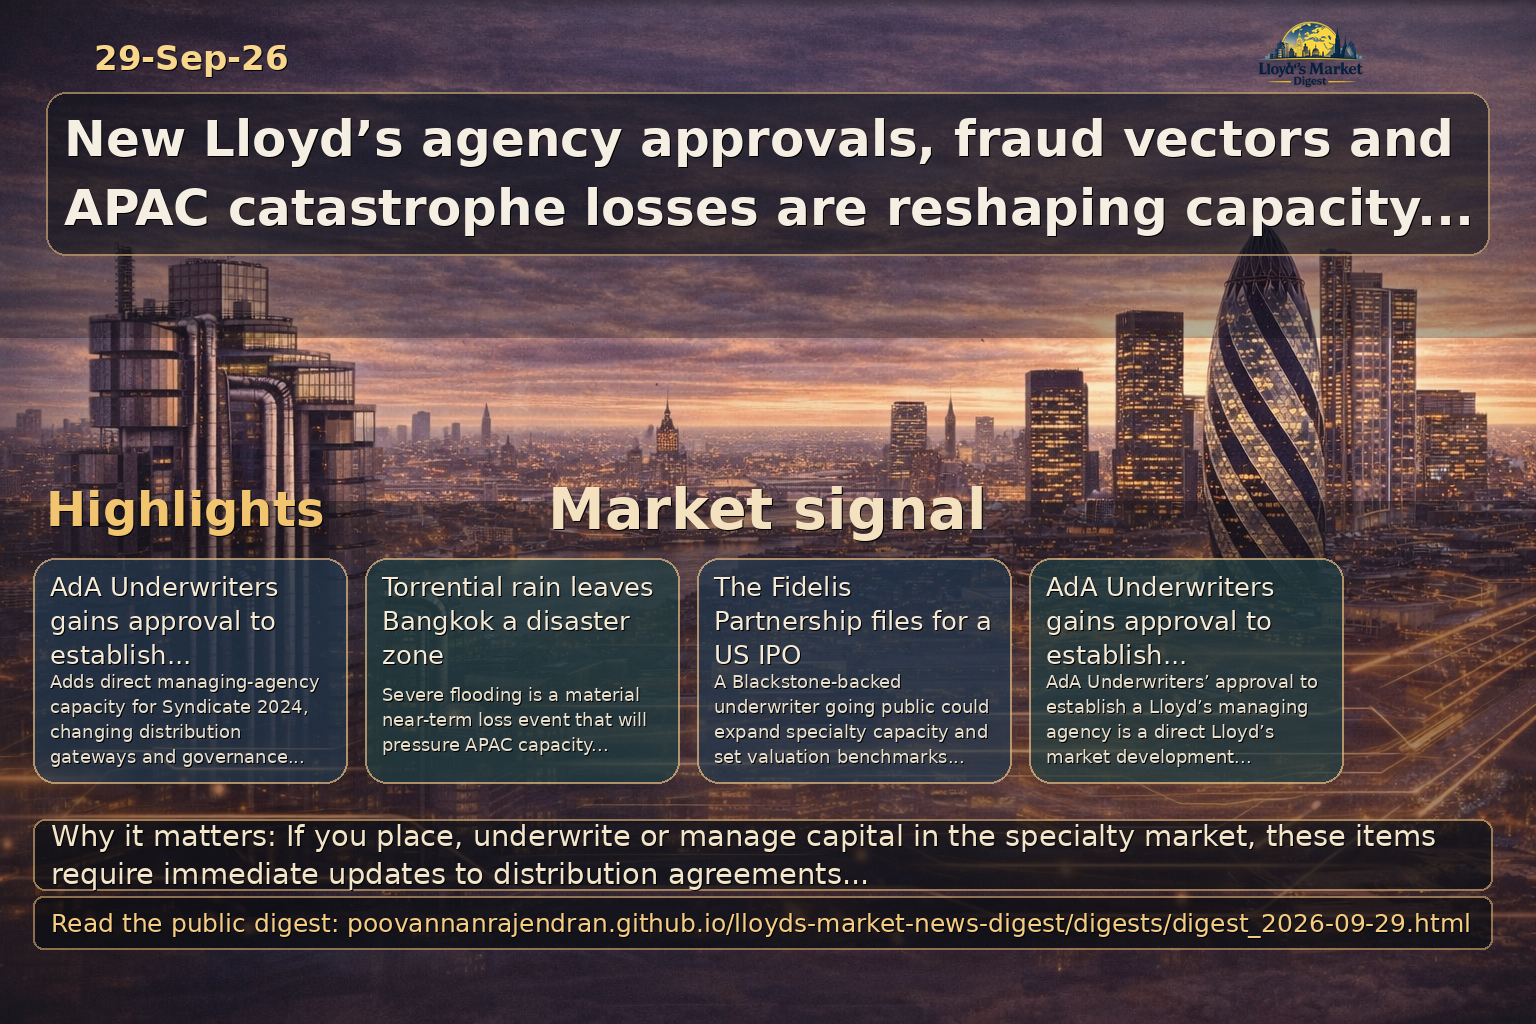
Why it matters: AdA Underwriters’ approval to establish a Lloyd’s managing agency is a direct Lloyd’s market development that will alter capacity, distribution relationships and governance for Syndicate 2024.
- Creates direct underwriting control and a formal Lloyd’s gateway that can attract both coverholders and brokers to Syndicate 2024.
- Signals continued evolution of Lloyd’s ecosystem—more teams converting SPAs and run-offs into full managing agencies to capture fee and underwriting economics.
- Requires brokers and placement platforms to update relationships and distribution strategies to reflect new agency structures and access protocols.
Source: fca.org.uk
Why it matters: FCA warning about an unauthorised site signals active consumer-targeting scams that can masquerade as insurance or placement services — a direct operational and reputational threat to brokers, platforms and syndicates when clients or capacity are exposed to fraudulent intermediaries.
- Immediate: Alert distribution partners and major clients to the specific domain; block and monitor referrals from flagged domains to placement platforms and broker portals.
- Control: Reinforce digital-vetting rules for third-party links and adverts on broker/portal environments; require proof of FCA authorisation or equivalent before onboarding any intermediary.
- Strategic: Incorporate domain-watching and automated threat feeds into compliance dashboards; run annual phishing and spoofing scenarios with claims teams and underwriting to test response readiness.
Source: fca.org.uk
Why it matters: A second FCA warning for a related app domain underscores the growing use of app-based or pseudo-app services to present unauthorised financial/insurance activity — a technological vector that can interface with placement platforms and broker tech stacks.
- Immediate: Require that platform integrations and mobile apps used by brokers prove regulatory status and provide contractually enforceable representation clauses on authorisation.
- Control: Implement API and app-store vetting in platform governance; block third-party app links unless they pass security and authorisation checks.
- Strategic: Add mobile-app and API risk assessments to vendor risk frameworks and include app-based scams in annual compliance training for brokers and syndicates.
Source: fca.org.uk
Why it matters: An FCA warning for legacytraderz.com is another example of unauthorised operators that can siphon client funds or misrepresent products — important for specialty brokers who place non-standard or complex risks and rely on client trust.
- Immediate: Communicate warnings to retail distribution networks and wholesale brokers to prevent client redirection to unauthorised sites.
- Control: Strengthen client acceptance procedures for new business sourced via online channels; insist on certified proof of intermediary status for higher-risk or non-standard placements.
- Strategic: Track aggregate referral flows and anomalies from online campaigns; collaborate with peers and trade bodies to create shared blacklists of high-risk domains.
Source: fca.org.uk
Why it matters: Administration of an authorised financial planning firm and its appointed representative illustrates the vulnerability of AR models and the continuity risk to customers — a model analogous to some broker-appointee relationships in insurance distribution that can expose syndicates to gaps in premium handling and claims servicing.
- Immediate: Review exposure to any brokers or advisers operating under AR arrangements; identify open placements or binding authorities where continuity plans are needed.
- Control: Require evidence of client money segregation, insurer remittance records and transfer plans for business in the event of insolvency as standard clauses in appointment agreements.
- Strategic: Build contractual and operational onboarding standards that mandate run-off and transfer provisions; maintain a prioritized list of critical counterparties with tested contingency arrangements.
Source: fca.org.uk
Why it matters: FCA recovery of funds in a £1.5m crypto fraud demonstrates both regulator capability and the material risk of fraud schemes that can touch insurance clients and market participants — relevant to underwriters of cyber, fidelity, and crime products and to brokers advising on digital-asset exposures.
- Immediate: Reassess client exposures and advice given around crypto-related investments and insured items; flag past placements with crypto exposures for possible claims or disputes.
- Control: For brokers and platforms, mandate enhanced due diligence and documentation when placing crypto-related risks; ensure clarity on policy wordings for digital asset coverage and exclusions.
- Strategic: Expand underwriting analytics to include fraud provenance scenarios; consider partnerships with recovery specialists and include clauses that facilitate cooperation with regulator-led recoveries.
Source: businessinsurance.com
Why it matters: Dunav's strong profitability in Serbia signals resilient local carrier economics that can influence regional capacity, ceding strategies and broker placement options relevant to Lloyd's and syndicates operating in the Balkans.
- Underwriting profitability may encourage Dunav to retain more risk locally, reducing ceded volume to international reinsurers and altering placement strategies for brokers.
- Profitable domestic carriers can become preferred regional partners for syndicates seeking distribution or coinvestment on specialty lines.
- Brokers and placement platforms should reassess panels and pricing assumptions for Balkan business given potential shifts in local capacity and appetite.
Source: businessinsurance.com
Why it matters: Qatar Insurance's targeted investment into Africa specialty risks expands a Gulf-based, balance‑sheet capital source into emerging markets—directly relevant to Lloyd's syndicates and global brokers managing Africa-facing placements.
- Adds alternative capacity to traditional Lloyd's and European reinsurers, affecting competition and pricing on Africa specialty risks.
- Creates opportunities for brokers to structure localized capacity solutions and reduce dependence on cross-border placements.
- May accelerate bespoke program structures that combine regional carriers with Lloyd's syndicates on higher layers.
Source: businessinsurance.com
Why it matters: Severe flooding in Bangkok is a material near‑term loss event that will impact APAC catastrophe modelling, reinsurance recoveries and pricing dynamics—critical for syndicates with regional exposure and brokers managing affected accounts.
- Immediate claims activity will pressure regional capacity and could prompt mid‑term repricing ahead of renewals for flood and allied perils.
- Tests catastrophe accumulation controls and retrocession arrangements for syndicates and global reinsurers.
- Drives demand for faster placement solutions (parametric covers, program layers) and increases the importance of efficient claims coordination via placement platforms.
Source: businessinsurance.com
Why it matters: Asia‑Pacific reinsurers expanding abroad intensify capital competition for specialty risks, changing how brokers and Lloyd's syndicates source and allocate capacity internationally.
- Non‑London capital entering international specialty markets creates pricing competition and alternative placement routes for brokers.
- Shifts the balance toward bilateral and regional placements, pressuring syndicates to demonstrate differentiated expertise and service.
- Encourages syndicates and placement platforms to refine product specialization and underwriting speed to retain mandates.
Source: businessinsurance.com
Why it matters: Settlement of a high‑profile asbestos reinsurance dispute reduces uncertainty around legacy liabilities and highlights the commercial imperative of clear reinsurance contract wording—critical for syndicate reserving and runoff strategies.
- Reduction in litigation exposure can materially affect reserves for legacy casualty portfolios across markets and influence M&A/runoff valuations.
- Reinforces the need for precise treaty language and dispute‑resolution mechanisms when structuring placements and facultative covers.
- May lead syndicates and reinsurers to revisit appetite for legacy liability portfolios and to refine placement platform due‑diligence on contract terms.
Source: globalreinsurance.com
Why it matters: Masojada’s likely mayoralty matters to Lloyd’s and the global specialty market because his profile as former Hiscox CEO confers sector-specific credibility, an influential City platform, and extensive relationships across brokers, syndicates and placement channels that can shape policy and market perception.
- Market advocacy and access: His mayoralty can amplify industry lobbying on regulation, international market access and competitiveness, benefiting Lloyd’s and specialty players seeking clearer engagement with UK authorities and overseas counterparts.
- Broker and syndicate relationships: Masojada’s network and sector reputation may facilitate dialogue and partnership between carriers, brokers and placement platforms, accelerating initiatives on distribution, capacity and product innovation while raising expectations of market stewardship.
- Governance and conflict management: His prior executive role underscores reputational upside but requires clear governance safeguards to manage perceived conflicts of interest between City duties and ongoing ties to insurers, ensuring transparent engagement with regulators, capital providers and market infrastructure operators.
Source: insurancejournal.com
Why it matters: The Fidelis Partnership filing for a US IPO is material to specialty insurance capital dynamics — a high-profile public listing by a Blackstone-backed underwriter affects available capacity, price discovery for specialty risk, and public-market governance expectations that ripple through Lloyd's, syndicates and broker relationships.
- Capital and capacity: A successful IPO could increase capacity available for specialty and layered placements, but public markets may drive greater earnings transparency and shorter-term return expectations that affect syndicate risk appetite.
- Valuation and competitor behavior: IPO pricing will be a benchmark for private capital and alternative capital providers, influencing M&A, reinsurance structures and pricing across specialty classes.
- Distribution & governance: Brokers and placement platforms will need to adapt to increased reporting/regulatory scrutiny of a public underwriter and may see shifts in appetite for delegated authority, MGA arrangements and alternative distribution channels.
Source: insurancejournal.com
Why it matters: High-severity lawsuits alleging traumatic brain injuries at a major amusement park amplify casualty and excess liability risk for operators and their insurers; verdicts or large settlements can recalibrate reserves and excess capacity for entertainment and leisure exposures.
- Claims severity and reserves: Potential for large injury awards increases pressure on primary and excess casualty reserves and can widen loss development assumptions for amusement/attraction portfolios.
- Underwriting & pricing: Syndicates writing US casualty/excess lines may tighten terms, increase pricing and apply tighter exclusions or enhanced safety-related warranties for entertainment clients.
- Broker advisory and data needs: Brokers must push for improved loss-control data, incident investigation clauses and stronger contractual risk transfer (indemnities/hold-harmless) in submissions to secure adequate capacity.
Source: insurancejournal.com
Why it matters: A major state settlement with a social platform over teen safety highlights regulatory-driven liability and class-action exposure for tech firms, with direct implications for D&O, media liability, cyber/privacy products and reinsurance appetite for technology sector risk.
- Regulatory-driven loss crystallization: Large settlements raise D&O and media liability loss expectations and may prompt capacity reduction or higher retentions for social-media clients.
- Policy terms and exclusions: Underwriters and reinsurers will scrutinize age-verification, moderation practices and regulatory compliance features; brokers should anticipate tighter policy language around regulatory defense/reactive remediation costs.
- Product and placement response: Placement platforms should prepare tailored cyber/privacy towers and crisis-response endorsements; brokers need to model potential regulatory aggregation for corporate tech accounts.
Source: insurancejournal.com
Why it matters: Severe flooding in Bangkok demonstrates acute urban flood risk and force-placed operational disruption in a major Asian hub — this informs catastrophe modeling, accumulation control and demand for property, BI and parametric solutions across global specialty markets.
- Catastrophe modeling and accumulation: Syndicates must reassess modeled losses and secondary perils accumulation in Southeast Asia; brokers should demand granular AAL and exposure analytics from underwriters.
- Product innovation: Elevated inland-urban flood frequency will increase interest in parametric triggers, flood excess protections and multi-peril BI products for global corporations and insurers.
- Placement and claims handling: Placement platforms and broker networks need streamlined local claims protocols and reinsurance recovery pathways to reduce settlement friction and speed capital relief.
Source: insurancejournal.com
Why it matters: Allegations that commodity contracts were forged and related judicial findings underscore systemic counterparty and documentation fraud — a salient issue for trade credit, crime/fidelity insurers and banks whose exposures can translate into claims and disputed recoveries.
- Crime and trade finance coverage: Insurers writing bank and commodity exposures will reassess policy wordings for fraud, forged documentation and KYC-triggered exclusions.
- Counterparty risk and reinsurance: Syndicates providing credit/reliance protection must heighten pre-placement due diligence and may demand stronger co-insurance or pricing for corrosive fraud risk.
- Broker advisory role: Brokers should enhance diligence on corporates' controls and recommend contractual protections (representations, warranties, escrow) to limit insurer losses and contested recoveries.
Source: insurancetimes.co.uk
Why it matters: Climate activism targeting a major insurer highlights reputational and regulatory scrutiny on fossil fuel exposures. For Lloyd's, syndicates and brokers this elevates the need for transparent ESG disclosure, underwriting governance and a coordinated communications posture across placements.
- Reputational pressure can accelerate appetite shifts and conditional exclusions for fossil fuel and LNG projects; syndicates should review live exposures and reinsurance terms.
- Brokers must prepare client-facing narratives and evidence of underwriting criteria and due diligence to manage placement friction and avoid allegations of greenwashing.
- Placement platforms and syndicate communications teams should coordinate rapid response playbooks and ensure ESG data points are accessible during submission and binding.
Source: insurancetimes.co.uk
Why it matters: The contextualised care framework for high-value pet claims affects specialty claims handling, reserving and the use of clinical data in decisioning. This has parallels for niche casualty and veterinary-adjacent specialty lines traded through Lloyd's and wholesale brokers.
- Adopting contextualised care will change claims variability and reserve adequacy; syndicates should pilot sampling of high-cost files and adjust pricing models accordingly.
- Brokers need guidance on evidentiary standards and how clinical judgement intersects with policy limits to preserve consumer trust and reduce disputes.
- Placement platforms and MGAs should evaluate integrations with veterinary data sources and workflows to support defensible, auditable claims decisions.
Source: insurancetimes.co.uk
Why it matters: Broker preference for in-house claims teams is reshaping commercial motor distribution. For Lloyd's syndicates and global specialty insurers, claims capability is now a competitive placement attribute affecting broker choice and retention.
- Insurers and MGAs with demonstrable in-house claims responsiveness gain market share; underwriting teams should consider claims capability as part of go-to-market strategy.
- Third-party claims providers risk losing placement volume unless they demonstrate tighter SLAs and transparent reporting to brokers.
- Placement platforms should present claims service metrics and integrate claims performance data into insurer profiles used by brokers during carrier selection.
Source: insurancetimes.co.uk
Why it matters: Alps placing a let property add-on suite on Acturis underscores the ongoing importance of platform distribution and product accessibility for brokers. For Lloyd's and specialty players, it reinforces the need for seamless connectivity to maintain broker flow and competitive presence.
- Platform integration reduces friction and accelerates placement velocity; syndicates and MGAs should prioritise connectivity to major broker trading systems.
- Bundled add-ons create cross-sell opportunities and require coordinated underwriting and claims rules to avoid post-bind disputes.
- Distribution teams must ensure data mapping and product governance are aligned with platform workflows to preserve pricing integrity and service levels.
Source: insurancetimes.co.uk
Why it matters: PPL's appointment of a chief product and technology officer signals accelerated investment in placement tooling, trading consoles and service benchmark intelligence for the London market. This will materially affect how syndicates, managing agents and brokers trade business.
- A consolidated product and technology leadership suggests faster roll-out of tools that will change submission, quoting and binding workflows; syndicates should engage early to influence requirements.
- Service benchmarking capabilities will make claims and service performance more visible; underwriters should prioritize measurable improvements to preserve broker relationships.
- Brokers and placement teams should prepare integration plans and internal change management for anticipated platform enhancements to avoid disruption during adoption.
Source: reinsurancene.ws
Why it matters: Historic archive content provides context on catastrophe loss experience and cyclical market pressures that remain directly relevant to Lloyd’s syndicates, reinsurers and brokers when assessing capital adequacy, modelling assumptions and underwriting cycles.
- Provides historical nat-cat loss benchmarks useful for syndicate capital and catastrophe modelling decisions
- Highlights past broker and reinsurer market commentary on discipline versus cost-of-capital—relevant to current pricing strategy
- Useful reference point for stress-testing underwriting assumptions and catastrophe aggregation scenarios
Source: reinsurancene.ws
Why it matters: Aon’s Power Lifecycle Program (PLP) demonstrates broker-led product innovation that aligns insurance placements across construction, commissioning and operations—critical for syndicates and placement platforms seeking gigawatt-scale energy project risk.
- Lifecycle placement reduces coverage gaps and simplifies investor/financier requirements for project sponsors and lenders
- Creates repeatable product opportunities for specialty syndicates to provide coordinated multi-stage capacity
- Signals demand for brokers and platforms to support end-to-end placement workflows and integrated documentation
Source: reinsurancene.ws
Why it matters: Tokio Marine GX launch marks a strategic commitment by a global insurer to consolidate renewable and transition risk underwriting—an important source of capacity and expertise that brokers and syndicates will need to access to scale green portfolios.
- Deploys specialist renewable underwriting expertise (GCube) into a global offering attractive to project sponsors and brokers
- Expands available capacity for renewable energy risks, reducing barriers for Lloyd’s syndicates to co-insure or lead placements
- Positions an established carrier as a partner for structuring transition-risk products and advisory services
Source: reinsurancene.ws
Why it matters: The creation of a partner ecosystem around Tokio Marine GX illustrates how insurers are broadening underwriting appetite across the green value chain—important intelligence for brokers and syndicates reassessing product portfolios and distribution partnerships.
- Ecosystem approach broadens underwriting appetite into niche transition risks (carbon credits, clean tech, nuclear) and diversifies premium streams
- Creates co-insurance and reinsurance opportunities for specialty syndicates seeking exposure to transition assets
- Indicates increased competition and partnerships in the green-specialty segment that brokers should leverage for client placement solutions
Source: risk.net
Why it matters: Risk.net highlights that physical-climate exposure is now a material input to credit assessments; this alters how brokers, syndicates and placement platforms manage counterparties, collateral and capacity.
- Reassess counterparty credit frameworks to incorporate forward-looking geospatial and scenario-driven physical-risk metrics; update limits and approval governance accordingly.
- Anticipate increased collateralisation and rating-triggered security demands from capital providers and reinsurers; review and renegotiate facility and broker of record arrangements.
- Require brokers and placement platforms to surface granular exposure data at binding to enable underwriters and capital providers to make informed credit and capacity decisions.