Source: fca.org.uk
Why it matters: An FCA warning that glasstradecap.com may be operating without authorisation. For Lloyd’s stakeholders this represents a direct fraud and mis-selling risk that can impact client funds, placement integrity and broker reputations if platforms or intermediaries fail to block or detect engagement with such entities.
- Immediate: Ensure all broker and placement-platform onboarding rules block domains on the FCA Warning List and flag any correspondence referencing the domain for manual review.
- Due diligence: Integrate automated FCA-list checks into KYC/AML and third‑party vendor screening; require written confirmation from counterparties on licence status before executing placements.
- Market controls: Syndicates and carriers should review delegated authority agreements and cash-handling policies to ensure consumer protections and recovery routes are defined if clients or intermediaries transact with unauthorised entities.
Source: fca.org.uk
Why it matters: The FCA warning about deepearmining.com signals active targeting by unauthorised firms. In a specialized insurance context, this presents elevated risk where niche commodity or mining-related programmes are distributed through digital channels or via international brokers with limited UK presence.
- Distribution hygiene: Require brokers to verify counterparty authorisation and ultimate beneficial ownership for commodity/mining accounts, and refuse placements routed through flagged domains.
- Platform risk mitigation: Placement platforms must implement domain-level blocking, phishing detection and transaction monitoring for transfers originating from or directed to flagged entities.
- Escalation and recovery: Establish incident playbooks that include client notification templates, interaction with the FCA/ombudsman, and contingency plans for re-routing business if an intermediary is found to be unauthorised.
Source: fca.org.uk
Why it matters: Verdantam.com appearing on the FCA Warning List indicates another instance of unauthorised activity that could be leveraged to impersonate brokers or to solicit premiums and deposits. This risks capital exposure, consumer harm and erosion of trust in placement platforms used by syndicates and global specialty brokers.
- Broker controls: Reinforce contractual obligations requiring brokers and coverholders to verify all client-facing digital marketing domains and platforms against FCA warnings before engaging or introducing business.
- Client protection: Ensure that policyholder communications explicitly state authorised contact points and the limits of Financial Ombudsman/FSCS cover if interacting with unverified intermediaries.
- Reputational monitoring: Maintain a watchlist of flagged domains and conduct periodic scans of inbound leads and email headers for spoofing attempts that could impersonate Lloyd’s brokers or MGAs.
Source: fca.org.uk
Why it matters: The FCA survey showing rising firm confidence, satisfaction and understanding of Consumer Duty presents an opportunity for the Lloyd’s market to capitalise on improved regulator relations while recognising heightened regulatory expectations around consumer protection, market integrity and conduct across distribution chains.
- Strategic engagement: Use the improved sentiment to seek clarity from the FCA on expectations for placement platforms, delegated authority oversight and cross-border distribution compliance, focusing on Consumer Duty application to specialty products.
- Compliance uplift: Translate Consumer Duty understanding into measurable KPIs for brokers, syndicates and platforms—e.g., evidence of fair outcomes, product governance reviews, and distribution oversight checkpoints.
- Operationalise trust: Invest in training, data capture and audit trails that demonstrate proactive supervision of brokers and coverholders, and publish concise governance statements to reassure stakeholders and rating agencies.
Source: artemis.bm
Why it matters: Plenum’s emphasis on subordinated insurance debt highlights a growing fixed-income alternative for investors and a complementary source of long-term capital for insurers and syndicates. For Lloyd’s and global specialty players, insurance debt is a lever to diversify capital structures and broaden investor bases beyond traditional equity and collateralised ILS.
- Capital strategy: Consider subordinated note issuance or structured debt instruments to lock in long-duration capital while preserving underwriting capacity and regulatory capital efficiency.
- Investor relations: Placement platforms and brokers should develop investor roadshows and credit disclosure packages tailored to fixed-income investors assessing insurer credit and recovery mechanics.
- Pricing and risk: Evaluate the yield premium (e.g., observed spread uplift) against solvency implications and covenant design to ensure subordinated instruments support balance-sheet resilience without diluting underwriting returns.
Source: artemis.bm
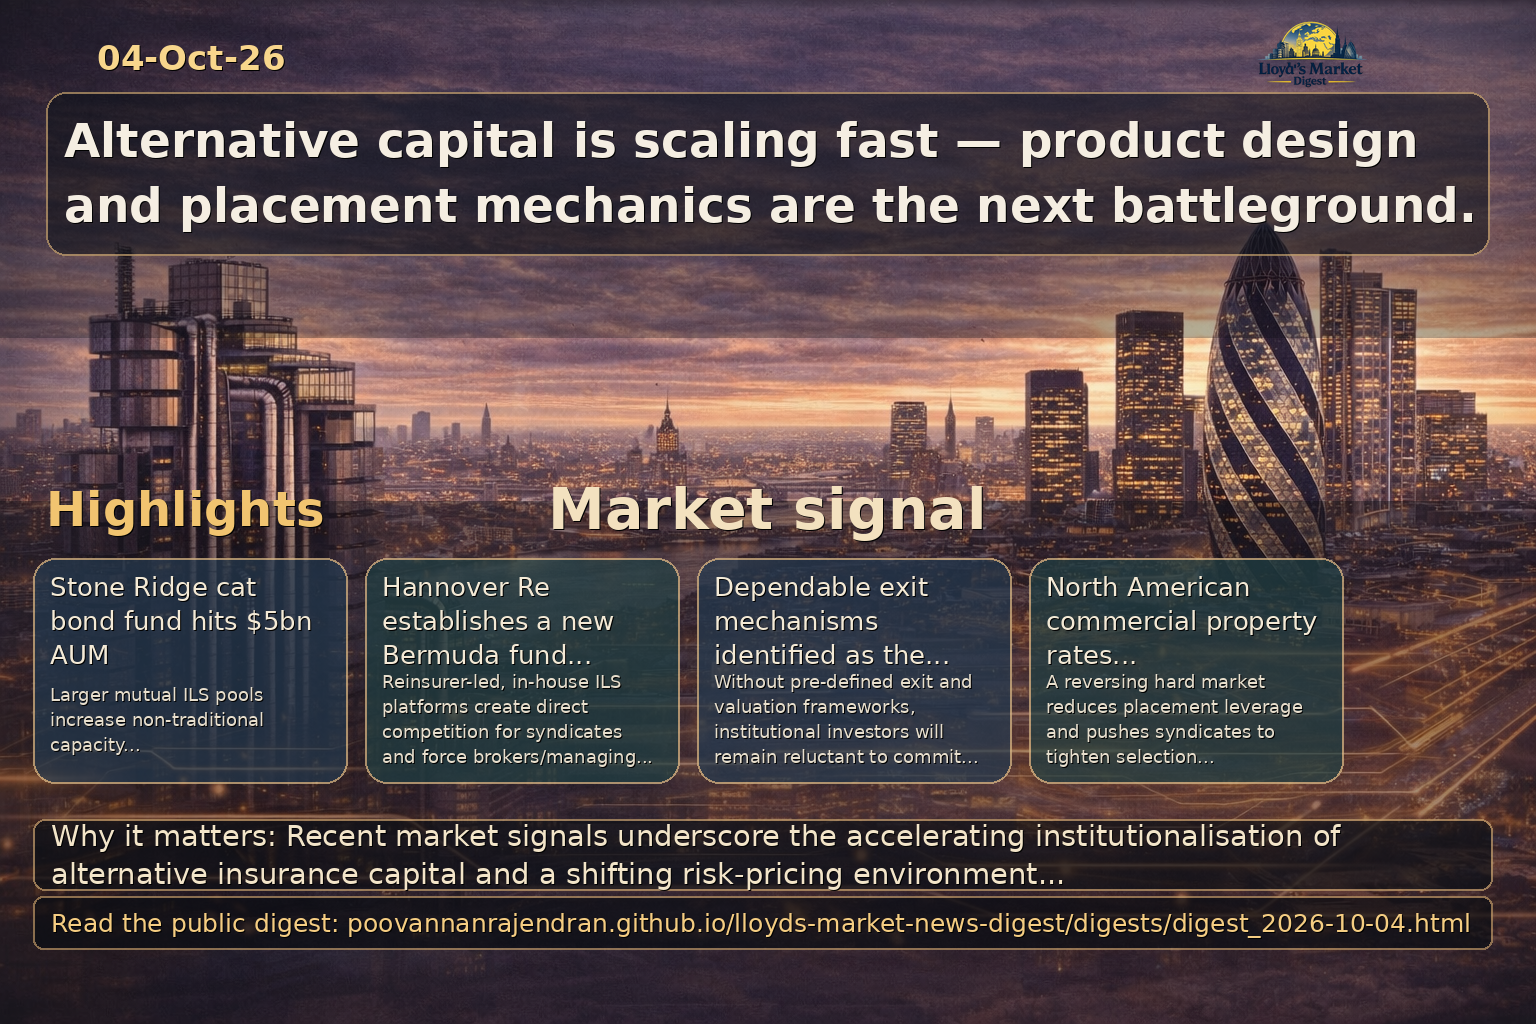
Why it matters: Willis’s report of sharp rate declines in North American commercial property signals a reversal of the multi-year hard market and a shift to abundant capacity. This has immediate consequences for placement leverage, broker strategy and syndicate underwriting discipline across specialty property portfolios.
- Underwriting response: Syndicates should tighten risk selection and focus on accumulation management and loss-prevention services rather than relying on rate to restore profitability.
- Broker strategy: Brokers can capitalise on abundant capacity to secure more favourable terms for clients, but must balance short-term pricing gains against client retention and long-term exposure build-up.
- Portfolio action: Placement platforms and syndicates should reallocate capital to specialty lines or alternative risk transfer mechanisms (including ILS) where pricing is more favorable, while monitoring the knock-on effects on collateral and retention levels.
Source: insurancejournal.com
Why it matters: ANZ's decision to drop a longstanding auditor underscores increased governance scrutiny and reputational fallout for professional service firms. For Lloyd's and specialty participants, such moves influence D&O and professional indemnity exposures, client operational continuity, and due-diligence expectations from brokers and placement platforms.
- Re-evaluate PI and D&O appetite and policy limits for audit firms and major service providers; clarify retroactive dates and run-off exposures.
- Require enhanced vendor-concentration and continuity disclosures from corporate clients during placement and renewal processes.
- Brokers and platforms should incorporate audit-transition and regulatory-change scenarios into risk presentations to syndicates and capital providers.
Source: insurancejournal.com
Why it matters: AXA losing a major institutional client due to geopolitical pressures illustrates how political campaigns and reputational exposures can abruptly terminate contracts. This dynamic affects underwriting of political risk, reputational liability, and continuity of coverage for public/international entities.
- Reassess political risk and reputational-liability products for exposures tied to international institutions and high-profile clients; ensure clear termination and lapse protections.
- Review contract wording for public and intergovernmental clients to address abrupt counterparty changes and replacement-provider risk.
- Encourage brokers to model reputational contagion scenarios and present mitigation (reinsurance/backstop capacity) to syndicates.
Source: insurancejournal.com
Why it matters: Arrests tied to plots near a military airbase elevate terrorism and state-involvement concerns for property, liability and political violence lines. For Lloyd's syndicates, concentrated exposures around critical infrastructure demand tighter aggregation controls and tailored wordings.
- Tighten aggregation monitoring and concentration limits for assets near critical military or dual-use infrastructure; revisit catastrophe modelling assumptions.
- Update terrorism/war policy wordings to reflect evolving threat vectors and consider parametric triggers tied to government advisories.
- Brokers should provide intelligence-led exposure briefs to underwriters, including security measures and homeland-security liaison information.
Source: insurancejournal.com
Why it matters: Reports of AI tools facilitating a large-scale bank hack highlight an inflection point in cyber risk: automated, adaptive attacks against financial institutions increase frequency and potential aggregation. Lloyd's cyber underwriters, brokers and platforms must adapt coverage, limits, aggregation modelling and response requirements accordingly.
- Update cyber aggregation models to account for AI-enabled attack campaigns and potential rapid lateral movement across financial systems.
- Introduce or tighten affirmative language on AI-agent-related exposures, incident response SLAs, and mandatory forensics/mitigation protocols in cyber placements.
- Brokers and platforms should require detailed cyber resilience evidence from financial-sector clients and coordinate with syndicates on capacity management and layered limits.
Source: insurancejournal.com
Why it matters: Everest's sale of Canadian retail operations to Wawanesa and Gallagher's NZ acquisition reflect ongoing distribution consolidation and strategic reallocation of specialty retail capacity. These transactions affect broker-syndicate relationships, access to retail pipelines, and opportunities for placement-platform consolidation or partnerships.
- Syndicates should reassess distribution strategies and partner criteria as regional retail platforms consolidate; prioritize channels that preserve specialty placement effectiveness.
- Brokers must evaluate how acquisitions change delegated authority, appetite, and servicing; update panels and binding arrangements accordingly.
- Placement platforms should explore strategic integrations or alliances to lock in access to redistributed retail flows and offer seamless submission routing to syndicates.
Source: insurancetimes.co.uk
Why it matters: Senior hires into an MGA building a private client personal lines proposition signal intensified competition for high-net-worth capacity and broker relationships; talent migration from legacy carriers accelerates product-market entry and credibility.
- Elevated market credibility: Recruiting an experienced HNW underwriter from Aviva fast-tracks product design, appetite setting and reinsurance conversations with specialty capacity providers.
- Broker engagement imperative: MGAs must convert executive reputation into distribution agreements and delegated authority flows with brokers servicing HNW clients.
- Syndicate/capacity impact: Underwriters moving from major carriers increase options for capacity partners but require clear governance and performance metrics to secure quota-share or delegated arrangements.
Source: insurancetimes.co.uk
Why it matters: Deloitte’s projection of up to £500m annual productivity gains via AI-enabled claims transformation is material for carriers and brokers managing expense ratios in a prolonged soft market; improvement in claims throughput directly affects underwriting economics and pricing flexibility.
- Strategic investment case: Syndicates and carriers should prioritise claims automation pilots that demonstrate measurable cycle-time and cost improvements to defend margins.
- Platform integration opportunity: Placement and broking platforms that incorporate AI-assisted claims triage will differentiate on service and reduce post-bind administration for brokers.
- Operational change management: Realising gains requires pairing technology with claims workforce re-skilling and revised SLAs to ensure complex claims retain expert handling.
Source: insurancetimes.co.uk
Why it matters: Senior leadership appointments at broker groups and wholesale brokers reflect consolidation and strategic repositioning in distribution; new executives will set priorities for capacity sourcing, digital placement and M&A activity.
- Distribution strategy reset: Incoming CEOs/CFOs will reassess carrier panels, delegated authority appetite and investment in placement technologies to capture share in specialty lines.
- M&A and scale play: Leadership changes often precede or follow bolt-on M&A—expect heightened diligence on scheme portfolios, underwriting platforms and tech-enabled capabilities.
- Talent and culture: Brokers must retain client-facing and technical underwriting talent during transitions to avoid disruption in syndicate placements and scheme performance.
Source: insurancetimes.co.uk
Why it matters: Market performance rankings and headline corporate restructurings (eg insurers recognised for solvency or executing job consolidations) influence capacity signals, reinsurer appetite and counterparty selection across specialty lines.
- Capacity selection criteria: Underwriters and brokers will increasingly reference independent solvency and performance metrics when allocating limited specialty capacity.
- Counterparty risk management: Syndicates and brokers should re-evaluate exposure concentrations to carriers undergoing restructuring or workforce reductions.
- Market reputation leverage: High-performing carriers can command improved terms and expand specialty capacity; brokers should quantifiably demonstrate referral quality when negotiating panels.
Source: insurancetimes.co.uk
Why it matters: Evidence of broker difficulty selling cyber cover in a soft market, combined with client cybersecurity skills gaps, highlights distribution and product development challenges for a key specialty line; brokers must balance placement volume with underwriting discipline and client risk mitigation.
- Product differentiation: Brokers should work with carriers to design modular cyber offerings that emphasise prevention services and clearer limits to restore underwriting discipline.
- Advisory uplift: There is a commercial opportunity for brokers to package cyber risk advisory and managed response services alongside cover to improve sell-through and loss outcomes.
- Risk selection scrutiny: Insurers and delegated authority providers must tighten submission standards and data quality to prevent adverse selection in a soft pricing environment.
Source: artemis.bm
Why it matters: Hannover Re’s establishment of Bermuda fund structures signals reinsurer-led verticalisation of ILS capability, increasing competition for risk capital and accelerating Bermuda as a placement and administration hub. This matters to Lloyd’s syndicates, brokers and placement platforms that compete for or collaborate with ILS-originating capacity and need to manage cross-jurisdictional execution.
- Strategic impact: Syndicates and brokers should map potential capacity shifts as global reinsurers build in-house ILS platforms and anticipate direct placement opportunities outside traditional Lloyd’s channels.
- Operational implication: Placement platforms and managing agents must ensure Bermuda-compatible documentation, tax and regulatory workflows to facilitate efficient collateralised deals and sidecars.
- Commercial action: Engage with reinsurer-run ILS managers for co-placement or distribution partnerships and reassess broker commission and service models to retain flows when counterparties move to captive ILS structures.
Source: artemis.bm
Why it matters: The Strategic Risk Solutions view that dependable exit mechanisms are the breakout factor for casualty ILS focuses attention on capital finality and liquidity design for long-tail exposures — a core concern for Lloyd’s syndicates that underwrite casualty and for brokers structuring transfers. Without credible exit paths investors will remain reluctant to commit sizeable, long-dated capital.
- Product design: Embed pre-defined exit triggers, valuation methodologies and capital-finality clauses at inception to make casualty ILS fungible to institutional investors.
- Placement mechanics: Placement platforms must support longer settlement cycles, escrow and valuation frameworks that reduce basis risk and provide investor confidence in monetisation options.
- Market development: Syndicates and brokers should collaborate on standardised documentation and third-party detachment/novel reinsurance wrappers to create a clearer secondary market and improve investor liquidity.
Source: artemis.bm
Why it matters: Stone Ridge’s cat bond fund reaching $5bn AUM (and $7.6bn across mutual ILS strategies) demonstrates continued institutional inflows and retail-channel scale. For Lloyd’s syndicates and brokers, larger mutual ILS pools increase the supply of non-traditional capacity but may compress spreads and alter placement dynamics.
- Supply-demand effect: Increased mutual ILS capacity can exert downward pressure on reinsurance pricing and widen capacity options for brokers, requiring syndicates to defend margin through underwriting selectivity.
- Distribution opportunity: Brokers and platforms should cultivate relationships with growing mutual fund managers to access stable pools of capital and co-develop issuance pipelines.
- Competitive positioning: Syndicates should assess product differentiation (e.g., structured triggers, coverage granularity) to remain attractive to both collateralised fund managers and traditional reinsurers.
Source: newsnow.co.uk
Why it matters: Search result failure highlights media-aggregation and vendor access issues that can produce intelligence blind spots for syndicates and brokers.
- Operational risk: gaps in third‑party search/indexing reduce timely detection of emerging reputational or loss events relevant to underwriting and claims.
- Vendor governance: brokers and MGAs should validate news/OSINT providers, enforce SLAs and run periodic accuracy checks to protect placement decisions.
- Mitigation: implement redundancy in feeds (direct local sources, proprietary monitoring) and integrate alerts into underwriting and trading desks to avoid delayed risk actioning.
Source: newsnow.co.uk
Why it matters: Absence of searchable content for a niche locale (Nantucket) suggests monitoring gaps for HNW, marine and seasonal property exposures important to specialty lines.
- Concentration awareness: Nantucket and similar locales can concentrate HNW property, yacht and seasonal casualty risks that require tailored capacity allocation and catastrophe modeling.
- Underwriting data: inadequate local reporting undermines exposure assessment for storm, flood and marine perils — brokers must supplement aggregator data with local intelligence and client disclosures.
- Placement strategy: consider bespoke policy wordings and facultative placements for high-value, low-frequency exposures; ensure platforms allow granular locality tagging.
Source: newsnow.co.uk
Why it matters: Developments in the Super League (expansion/format changes) increase aggregate sports and event insurance exposures for specialty syndicates and brokers.
- Capacity implications: league expansion expands event frequency and aggregate liability — syndicates must reassess exposure accumulation and reinsurance arrangements.
- Product design: clubs’ changing financial profiles require flexible covers (player injury, event cancellation, D&O, sponsor breach) and mid‑season endorsements on placement platforms.
- Broker actions: update appetite matrices, scenario modelling and client advisory materials; ensure marketplaces can support scalable multi-event programmes.
Source: newsnow.co.uk
Why it matters: Wakefield Trinity’s profile highlights classic specialty exposures: older stadia, historic club asset risks and concentrated local liability needs.
- Property & infrastructure: historic venues often present maintenance and latent defect risks—underwriters should re-examine sum insured, replacement cost and latent defect clauses.
- Casualty & event risk: player injuries and spectator liability require integrated casualty, event cancellation and public liability solutions tailored to lower-tier clubs.
- Community & reputational: local clubs have strong community profiles; brokers should advise on crisis response clauses and reputational risk components in programmes.
Source: newsnow.co.uk
Why it matters: Local Wakefield developments (e.g., clinical trials centre expansion) signal underwriting opportunities and operational risks in clinical trials and medical-related specialty lines.
- Underwriting opportunity: expansion of trials facilities increases demand for clinical trials liability, CRO coverages and medical malpractice extensions for specialty underwriters.
- Operational exposures: construction, commissioning and operational BI risks require tailored property, construction all-risk and business interruption solutions.
- Regulatory & compliance: brokers must ensure placement platforms capture regulatory credentials, indemnities and data privacy obligations for trial sponsors and sites.
Source: risk.net
Why it matters: The guide’s emphasis on machine-ready, governed cloud data directly addresses bottlenecks in syndicate pricing, broker bind workflows and platform reconciliation, making it highly relevant to Lloyd’s market participants seeking faster, lower-cost placements.
- Reduce reconciliation and operational overhead: standardised cloud data eliminates repeated file transfers and bespoke adapters between brokers, MGAs and syndicates, lowering manual effort and settlement friction.
- Enable real-time pricing and automated binding: machine-ready reference and pricing data accelerates model deployment into placement platforms and underwriting workbenches for quicker quotes and capacity allocation.
- Strengthen governance and regulatory readiness: centralised, auditable cloud data simplifies reporting to managing agents, regulators and capital providers while supporting model governance and explainability.